This guide explains practical 401(k) Caesars Entertainment strategies while keeping the focus on general retirement planning principles. Because employer plan provisions can change, employees should always review their current plan documents and account information before making financial decisions.
Understanding How a 401(k) Can Support Retirement Growth
A 401(k) is designed to help employees save for retirement through payroll contributions. Depending on the plan, contributions may be made on a traditional pre-tax basis, through Roth contributions, or through other available options.
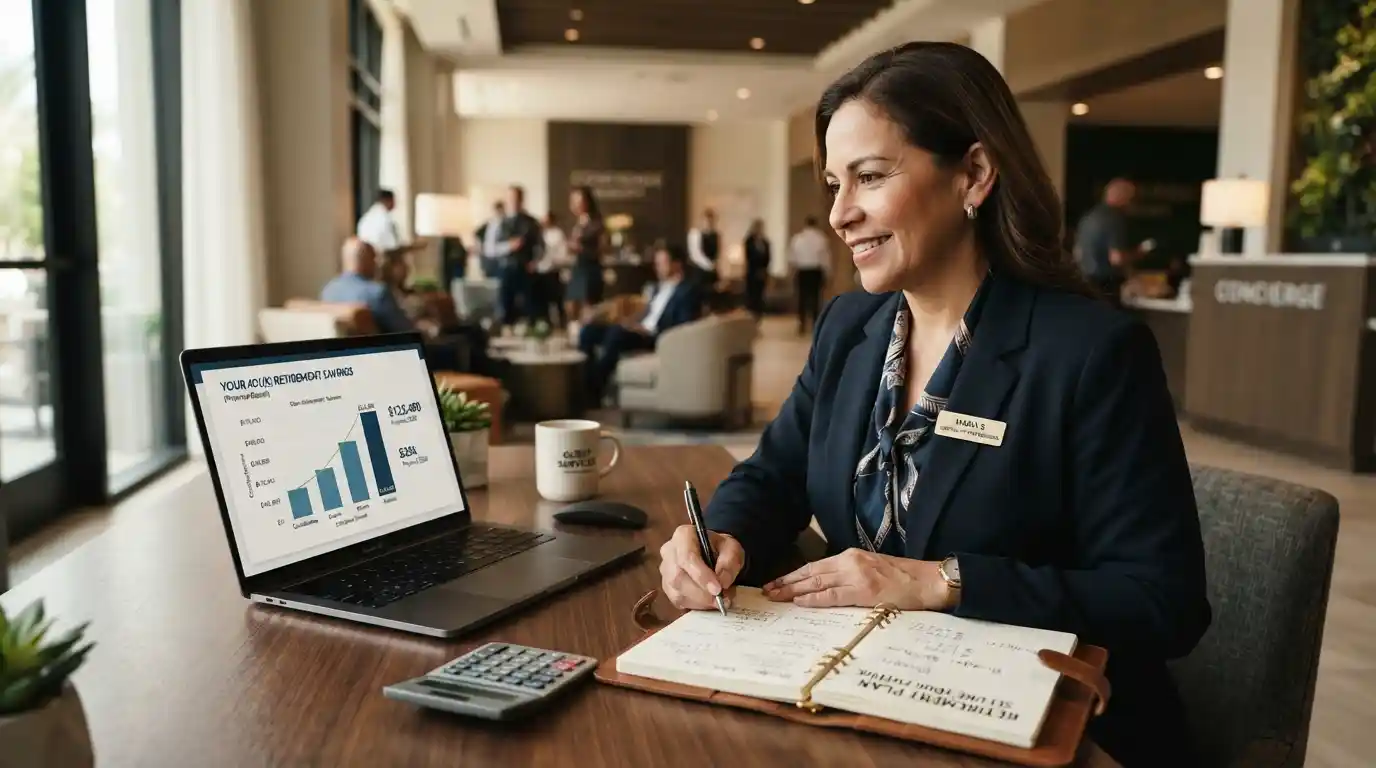
The major advantage of consistent retirement saving is time. Contributions made over many years can potentially benefit from compound growth, meaning investment earnings can generate additional earnings over time.
For employees who are also researching broader financial solutions, retirement savings should be considered alongside emergency savings, debt management, insurance, and other long-term financial goals.
Start With Your Current Caesars Entertainment 401(k) Plan Details
Before changing contribution rates or investment selections, review the specific provisions available through your current employer-sponsored plan. Important details can include eligibility requirements, contribution options, employer contributions, vesting rules, investment choices, fees, withdrawal provisions, and account-management procedures.
Do not rely on older descriptions of a workplace retirement plan. Employers can modify plan designs, investment menus, contribution structures, and administrative arrangements over time. Your current Summary Plan Description and plan portal should take priority when determining what applies to you.
1. Capture Any Available Employer Contribution
If your current plan provides an employer matching contribution, understand how the match works and what contribution level is required to receive the available benefit. An employer contribution can increase the amount being invested for retirement without requiring the employee to contribute the entire amount independently.
Check whether the match has a contribution limit, whether there are timing requirements, and whether employer contributions are subject to a vesting schedule. These details can make a meaningful difference over a long working career.
2. Increase Contributions Gradually
Saving a large percentage of income immediately is not practical for everyone. A gradual approach can be easier to maintain.
For example, an employee could increase their contribution rate after receiving a raise, paying off a loan, or reducing another recurring expense. Small increases repeated over many years can substantially change the amount going toward retirement.
This approach also creates a useful connection between career development and financial planning. As income changes, retirement contributions can be reviewed rather than leaving the original percentage unchanged indefinitely.
3. Understand Traditional and Roth Contributions
If both traditional and Roth contributions are available, understand how their tax treatment differs before selecting an approach.
Traditional 401(k) contributions generally receive tax treatment different from Roth contributions, while qualified Roth withdrawals can receive different tax treatment in retirement. The appropriate mix depends on individual circumstances, income, tax considerations, and expectations about future retirement income.
Because tax rules can change and personal circumstances vary, employees should consider consulting a qualified tax or financial professional when making significant retirement decisions.
4. Review Your Investment Allocation
Contributing money to a 401(k) is only one part of retirement planning. Employees also need to understand how their account is invested.
A workplace plan may offer several types of investment options, such as stock funds, bond funds, target-date funds, or other investment vehicles. Each option can have different levels of risk, potential return, diversification, and cost.
Your investment allocation should reflect factors such as your time until retirement, financial goals, risk tolerance, and other assets. Younger investors with decades before retirement may have different considerations from someone approaching retirement.
5. Avoid Concentrating Too Much in One Investment
Diversification can help reduce the impact of poor performance from any single investment or asset category. Concentrating retirement savings in one company, sector, or narrow investment can create additional risk.
Review the overall composition of your retirement portfolio instead of evaluating individual investments in isolation. Your 401(k) should also be considered alongside investments held elsewhere.
6. Pay Attention to Investment Fees
Investment fees can affect long-term retirement results because costs are deducted from investment returns or account balances. Even seemingly small differences in expenses can compound over a long period.
Review the expense information associated with available investment options and compare costs within the plan where appropriate. Lower cost does not automatically make an investment suitable, but understanding costs is an important part of evaluating retirement investments.
7. Build an Emergency Fund Outside the 401(k)
A retirement account is designed primarily for long-term savings, not everyday emergencies. Maintaining accessible emergency savings can reduce the temptation to take an early distribution or loan from retirement funds when unexpected expenses occur.
An emergency fund can be particularly valuable for employees managing changing household expenses, housing costs, debt payments, or other financial obligations.
For readers interested in broader financial topics, our guide to finance and repossession considerations provides additional context around financial obligations and planning.
8. Coordinate Retirement Saving With Other Financial Goals
Retirement saving should not be viewed in isolation. A complete financial strategy may include an emergency fund, debt repayment, insurance, education expenses, home ownership, and other long-term goals.
Someone carrying expensive debt may need to balance additional retirement contributions with debt reduction. Another employee may have sufficient emergency savings and be in a stronger position to increase retirement contributions.
There is no single contribution rate that works for every household. The important step is to establish a sustainable strategy and revisit it as circumstances change.
9. Think About Retirement as a Long-Term Process
Retirement planning works best as an ongoing process rather than a one-time decision. Income, family circumstances, investment preferences, tax rules, and retirement goals can all change over time.
Consider reviewing your 401(k) at least periodically. Look at your contribution rate, investment allocation, account fees, beneficiary information, and progress toward your broader retirement objectives.
10. Understand What Happens When You Change Jobs
Career changes can create important retirement-planning decisions. When leaving an employer, employees may have several options depending on the circumstances and applicable plan rules.
Possible considerations can include leaving assets in the former employer’s plan when permitted, rolling eligible assets into another qualified retirement account, or evaluating other available choices.
Before moving retirement assets, review fees, investment options, tax consequences, and administrative differences. A rollover should be evaluated carefully rather than treated as an automatic step.
Career planning and retirement planning often overlap. For additional career-related reading, see our coverage of career opportunities and professional growth and career development strategies.
11. Consider Beneficiary Designations
Your retirement account beneficiary designation is an important administrative detail that should not be overlooked. Review the designation after major life events such as marriage, divorce, the birth of a child, or other significant changes in family circumstances.
Beneficiary rules can be complex, so significant changes may warrant professional guidance. Keep beneficiary information consistent with your broader estate-planning documents where appropriate.
12. Avoid Treating Retirement Savings Like a Short-Term Investment
Market fluctuations are an unavoidable part of investing. A temporary decline does not necessarily mean a long-term retirement strategy has failed.
Making frequent investment changes based solely on short-term market movements can interfere with a carefully constructed long-term strategy. Instead, evaluate whether your investment allocation still matches your goals and time horizon.
13. Connect Retirement Planning With Broader Economic Conditions
Inflation, interest rates, employment conditions, and broader economic trends can affect household finances and retirement planning. Understanding these factors can provide useful context, although short-term economic headlines should not automatically dictate long-term investment decisions.
For broader economic context, explore our coverage of global economic shifts and economic impact and business conditions.
14. Keep Lifestyle Spending in Perspective
Retirement planning is ultimately connected to the lifestyle you expect to maintain later in life. Understanding current spending patterns can help you estimate the income you may need after leaving the workforce.
Entertainment, travel, dining, housing, healthcare, transportation, and personal interests can all affect future expenses. Planning for retirement therefore involves more than choosing an investment percentage.
For readers interested in the broader entertainment and lifestyle sector, see our coverage of entertainment experiences and lifestyle experiences in Kansas City.
15. Separate Retirement Investing From Gambling
Entertainment and gaming businesses can make retirement planning topics particularly relevant, but retirement investments should not be confused with gambling or speculative activity.
A retirement portfolio should be constructed around a defined financial objective, time horizon, diversification strategy, and risk framework. Short-term speculation can expose retirement assets to risks that may not align with long-term financial needs.
WayfareHub also covers casino and gaming-related topics, including casino entertainment, casino collectibles, and gaming-industry employment.
16. Use Career Growth to Strengthen Retirement Savings
Increasing income can create additional opportunities to improve retirement contributions. Professional development, career advancement, and new employment opportunities may eventually increase the amount available for long-term saving.
Employees can consider directing part of future salary increases toward retirement rather than allowing every increase in income to become an increase in lifestyle spending.
Other career and employment resources on WayfareHub include technology career opportunities and gaming-industry career information.
17. Reassess Your Strategy as Retirement Gets Closer
Your retirement strategy may need to evolve as your retirement date approaches. The appropriate balance between growth-oriented and more conservative investments can change as the time available to recover from market declines becomes shorter.
Near retirement, it can also become increasingly important to understand how withdrawals, Social Security, healthcare expenses, taxes, and other income sources may fit together.
Frequently Asked Questions About 401(k) Caesars Entertainment Planning
What is the best 401(k) contribution percentage?
There is no universal percentage that works for every employee. A useful starting point is to understand the available employer contribution and then determine a sustainable savings rate based on income, expenses, debt, age, and retirement goals.
Should I increase my Caesars Entertainment 401(k) contributions?
An increase may make sense when your household budget allows it, particularly after a raise or reduction in expenses. Review the current plan rules and your overall financial situation before making changes.
Should I choose traditional or Roth 401(k) contributions?
The choice depends on your current tax situation, expected future tax circumstances, retirement timeline, and personal financial strategy. If both options are available, understanding their different tax treatments can help you determine an appropriate allocation.
What should I do with my 401(k) after changing jobs?
Review the available options carefully. Depending on the circumstances, you may be able to leave the account where it is, roll eligible assets into another qualified retirement account, or consider another permitted option. Tax and investment implications should be reviewed before making a decision.
How often should I review my retirement account?
A periodic review can help ensure that your contribution rate, investment allocation, beneficiary information, and overall strategy continue to match your circumstances. Major life or career changes are also good reasons to revisit your plan.
Final Thoughts
A workplace 401(k) can become a valuable component of long-term retirement planning when it is used consistently and reviewed thoughtfully. For Caesars Entertainment employees, the most useful approach is to understand the current plan rules, capture available employer benefits when appropriate, maintain a sustainable contribution strategy, review investment choices, control unnecessary costs, and coordinate retirement savings with the rest of the household financial plan.
The key is consistency. Retirement growth generally depends on a combination of time, contributions, investment performance, and disciplined financial decisions. Rather than attempting to predict every market movement, focus on creating a retirement strategy that can be maintained and adjusted as your career and financial circumstances evolve.